Orlando Calvo Quant Demo Portfolio
My projects reflect my interest in finance, UI design, and performant analytics. I build tools for research and strategy development that aim to scale in cross-asset environments.
Selected Demos
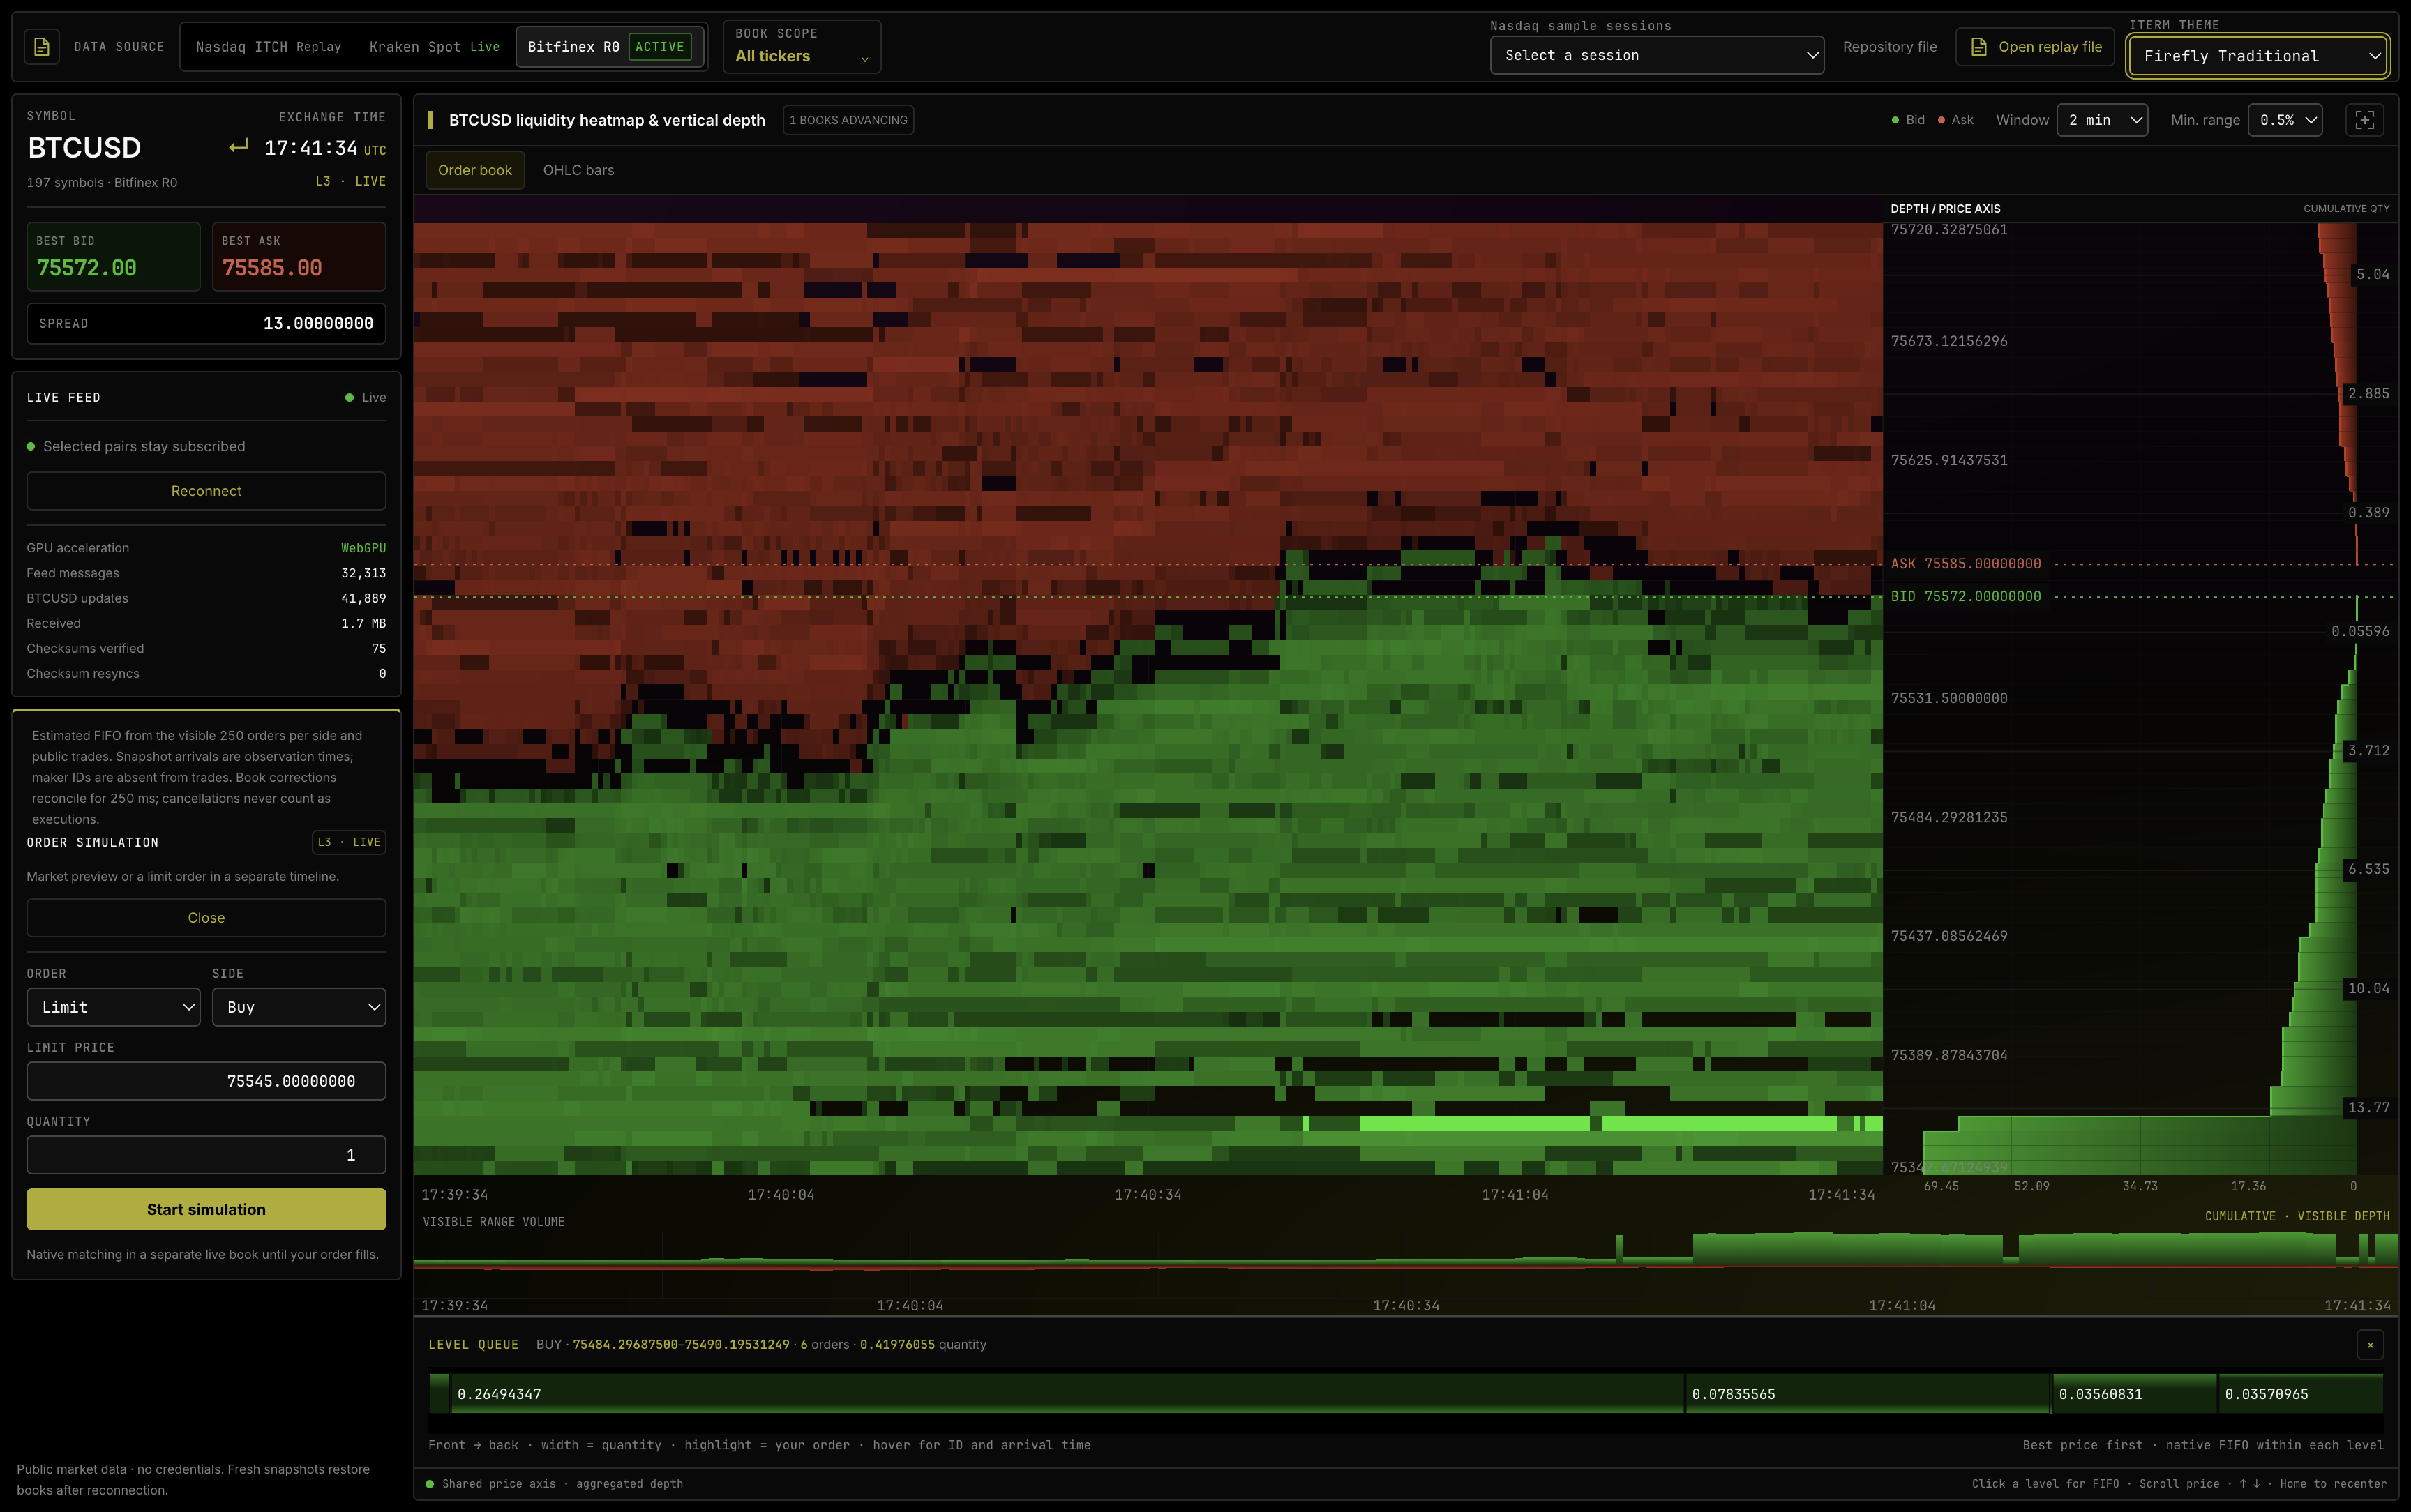
LOBO - Limit Order Book
Run with uv
uvx pylobo demo
Description
LOBO is a high-performance orderbook built entirely in Rust and fully accessible through python bindings. It is designed for fast replay and simulated execution for market impact analysis. LOBO includes a custom python adapter API that allows you to build market data adapters to binary and json data sources. LOBO JIT compiles your python adapters to achieve intake speeds that are on-par with existing fully native zero-allocation rust adapters, allowing you to achieve blazing fast replay solely through your python implementation.
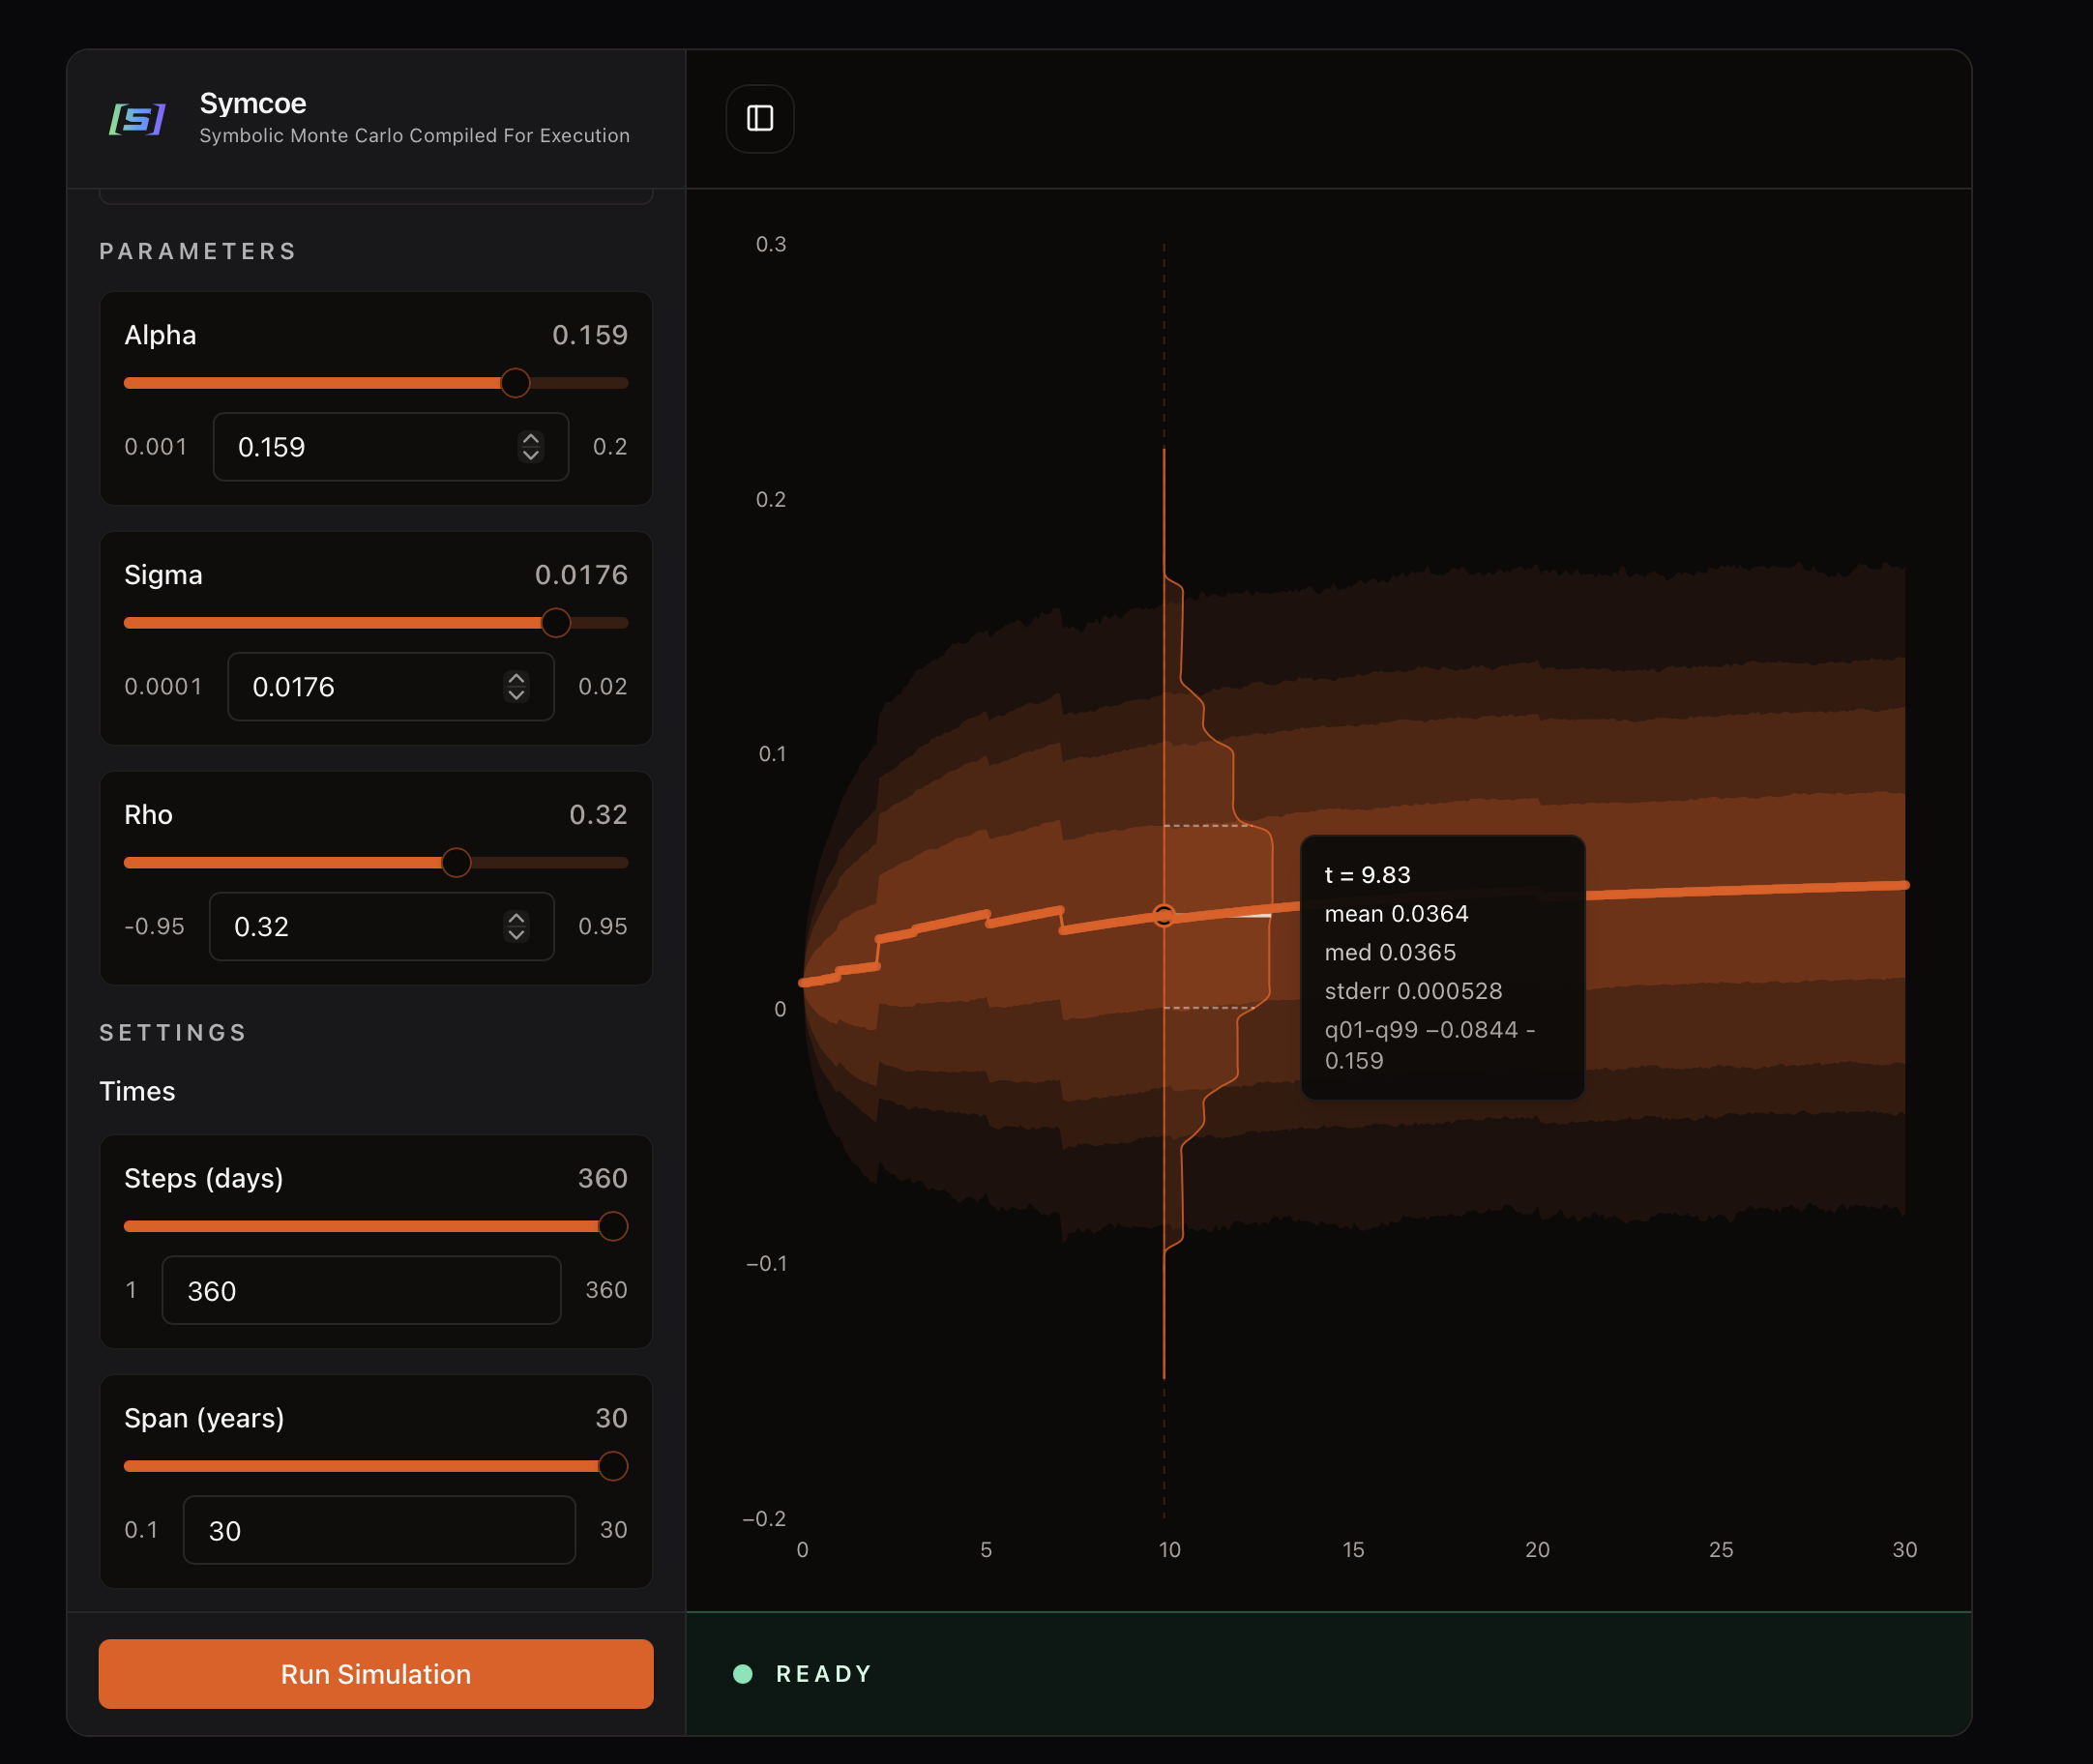
Symcoe Interest Rate Simulations
Description
Interactive examples of interest rate term structure models built with Symcoe. Symcoe enables the fast on-boarding of strategies by providing an api capable of expressing any simulation model in terms of its stochastic differential equations alone.
Tick Data API
Description
This notebook uses a market data client I designed for ML feature extraction and research. It queries a massive tick database and aggregates ohlcv bars according to the specified parameters. Bars are aggregated by time, tick, volume, and dollar values to make the time series friendlier for ML models. Instructions are provided on downloading the data set, but by default it runs off a very rate-limited endpoint tied to my own Snowflake account, for demonstration purposes.
SOFR Swap Pricing
Description
The site lets you see the real-time pricing of SOFR swaps. Market data can be bumped or sped up. Pricing happens through Taylor approximations. Sort through 5MM swaps and click on any one of them. You can see its details, risk, cashflows, and fixings. Daily fixings tick along with market data. You can revalue the swap. Click on the counterparty and you see the aggregation of all swaps with that counterparty — the ticking exposure and binned distribution of ticking expected cashflows.